Autumn Budget 2026: Five talking points for speciality food and drink
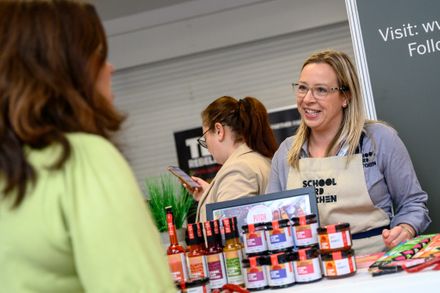
For independent food retailers, artisan producers and emerging British brands, the Autumn Budget brings a mixture of business rates support, changes to import costs and continued pressure on margins.
Whether running a deli, developing a range of preserves or sourcing speciality products from overseas, businesses will need to consider how the announcements affect their costs, customers and suppliers.
Here are five key talking points for the speciality food and drink community.
1. Business rates relief could benefit delis, farm shops and independent retailers
From April 2027, qualifying retail properties in England will receive full Small Business Rates Relief up to a rateable value of £18,000, increased from £12,000. Tapered relief will extend to £21,000, up from £15,000.
For eligible delis, food halls, convenience stores and other independent food shops, this could reduce a significant fixed cost.
Qualifying retail, hospitality and leisure properties will also have business rates increases capped at CPI inflation in 2027–28 and 2028–29, subject to exceptions. This is a real-terms freeze, so bills can still increase in cash terms.
Andrew Goodacre, CEO of the British Independent Retailers Association (Bira), welcomed the announcements as “a real win for independent retailers”.
Farm shops and producer cafés may also qualify, depending on property use and eligibility. However, a production kitchen or workshop does not automatically qualify for retail or hospitality relief.
For businesses combining production with a shop or café, understanding how their premises are assessed will be particularly important.
2. Import tariff changes present a mixed picture for speciality sourcing
Tariffs on selected food imports will be suspended from 26 November 2026 until 31 December 2028. Covered products include specified chocolate, dried fruit and plant-based drinks, although the precise tariff classification will determine eligibility.
For speciality importers and producers buying affected ingredients, the changes could offer purchasing savings. Retailers sourcing through distributors may also benefit if reductions are passed through.
However, the implications differ for British brands competing with imported finished products.
Karen Betts, Chief Executive of the Food and Drink Federation (FDF), warned that removing tariffs from some food and drink products would have “no meaningful impact on consumer prices”, while undermining British factories producing competing goods.
This adds another consideration to buying decisions that already balance quality, provenance, price and supplier relationships. Lower import costs may create opportunities, but the commercial pressures facing domestic producers also matter to the future of distinctive British ranges.
Existing business tariff suspensions are also being extended for covered inputs. A new application window, running from 11 November 2026 to 3 February 2027, will allow businesses to request additional suspensions, with approval subject to assessment.
3. Higher employment costs will affect shops and small producers
From April 2027, the National Living Wage for workers aged 21 and over will increase by 50p to £13.21 an hour. Minimum hourly rates will rise to £11.27 for 18 to 20-year-olds and £8.31 for under-18s and eligible apprentices.
For businesses making products in small batches, staffing a deli counter or packing online orders, higher wages will add to operating costs.
Goodacre expressed disappointment at the lack of further support for small employers, saying: “Increasing the Employment Allowance would have been a real help to small employers, and this was a missed opportunity.”
The implications extend beyond payroll. Labour requirements, ingredient costs, packaging and delivery all influence the price needed to make a product commercially sustainable.
Retail buyers may therefore see continued pressure in supplier price discussions. Understanding the work behind a product, alongside its customer appeal and retail margin, will remain important when assessing a range.
4. Small drinks producers receive targeted support alongside duty increases
Alcohol duty will rise in line with RPI from 1 February 2027, affecting relevant producers, importers and retailers.
At the same time, Small Producer Relief will become more generous for qualifying alcohol producers. Changes include an improved discount taper for products below 3.5% ABV and an increase in the marginal discount for products between 3.5% and 8.4% ABV.
For eligible independent breweries and other qualifying producers, this could provide additional support for investment and product development. It is a producer relief, so retailers should not assume it will automatically reduce wholesale prices.
Andy Slee, Chief Executive of the Society of Independent Brewers and Associates (SIBA), welcomed the changes, highlighting their potential to help smaller breweries compete and develop lower-strength beers.
Higher Soft Drinks Industry Levy rates from April 2027 will also be relevant to liable soft drinks stocked by speciality retailers. The combined changes make it worth discussing product-level implications with suppliers, particularly when planning new listings, promotions and seasonal ranges.
5. Emerging brands should review support for starting and growing
For individuals taking their first steps into food and drink, the Trading Allowance will increase from £1,000 to £3,000 from 6 April 2027.
This provides relief for qualifying trading and miscellaneous income and could be relevant to very small ventures or side businesses. It is not a general £3,000 tax exemption for every food company.
Businesses looking further ahead may also find opportunities through expanded UK Export Finance support, including a new SME export finance scheme planned for 2027. Subject to eligibility, this could help smaller brands finance export activity and develop overseas sales.
Chris Martin, Corporate Affairs Director at the Chartered Institute of Export & International Trade, emphasised the importance of helping businesses build the capability to trade internationally.
“The UK’s long-term growth depends not only on domestic investment, but on helping more businesses export successfully, diversify into new markets and build resilient international supply chains,” he said.
For brands selling through online marketplaces, changes from October 2027 will also affect how VAT is collected on relevant sales. Businesses should follow their platforms’ guidance as implementation approaches.
The practical focus remains on building sustainable businesses around distinctive products, strong supplier relationships and a clear understanding of customers.
These conversations will continue at Speciality & Fine Food Fair, part of Food, Drink & Hospitality Week, taking place at Excel London on 5–7 April 2027. The event will bring speciality retailers, artisan producers and food and drink brands together to discover products, develop relationships and explore opportunities for growth.